2025Section 2
2. Definitions.
In the 1961 Act143 matches · Unreviewed
- 1961 Section 2
- 2(4) → 1961 2(1)
- 2(16) → 1961 2(10)
- 2(17) → 1961 2(11)
- 2(18) → 1961 2(12)
- 2(19) → 1961 2(12A)
- 2(20) → 1961 2(13)
- 2(21) → 1961 2(13A)
- 2(22) → 1961 2(14)
- 2(23) → 1961 2(15)
Show all 143
- 2(24) → 1961 2(15A)
- 2(25) → 1961 2(15B)
- 2(26) → 1961 2(16)
- 2(27) → 1961 2(16A)
- 2(28) → 1961 2(17)
- 2(29) → 1961 2(18)
- 2(32) → 1961 2(19)
- 2(36) → 1961 2(19A)
- 2(35) → 1961 2(19AA)
- 2(34) → 1961 2(19AAA)
- 2(37) → 1961 2(19C)
- 2(5) → 1961 2(1A)
- 2(6) → 1961 2(1B)
- 2(2) → 1961 2(1C)
- 2(3) → 1961 2(1D)
- 2(7) → 1961 2(2)
- 2(38) → 1961 2(20)
- 2(39) → 1961 2(21)
- 2(40) → 1961 2(22)
- 2(42) → 1961 2(22A)
- 2(41) → 1961 2(22AA)
- 2(43) → 1961 2(22AAA)
- 2(44) → 1961 2(22B)
- 2(45) → 1961 2(23)(i)
- 2(74) → 1961 2(23)(ii)
- 2(75) → 1961 2(23)(iii)
- 2(46) → 1961 2(23A)
- 2(48) → 1961 2(23C)
- 2(49) → 1961 2(24)
- 2(51) → 1961 2(25)
- 2(52) → 1961 2(25A)
- 2(53) → 1961 2(26)
- 2(55) → 1961 2(26A)
- 2(56) → 1961 2(26B)
- 2(57) → 1961 2(28)
- 2(59) → 1961 2(28A)
- 2(60) → 1961 2(28B)
- 2(58) → 1961 2(28BB)
- 2(62) → 1961 2(28C)
- 2(63) → 1961 2(28CA)
- 2(64) → 1961 2(28D)
- 2(65) → 1961 2(29)
- 2(66) → 1961 2(29A)
- 2(67) → 1961 2(29AA)
- 2(68) → 1961 2(29B)
- 2(69) → 1961 2(29BA)
- 2(70) → 1961 2(29C)
- 2(72) → 1961 2(30)
- 2(77) → 1961 2(31)
- 2(79) → 1961 2(32)
- 2(80) → 1961 2(33)
- 2(81) → 1961 2(34A)
- 2(82) → 1961 2(34B)
- 2(83) → 1961 2(34C)
- 2(84) → 1961 2(34D)
- 2(85) → 1961 2(35)
- 2(86) → 1961 2(36)
- 2(88) → 1961 2(36A)
- 2(89) → 1961 2(37)
- 2(90) → 1961 2(37A)
- 2(91) → 1961 2(38)
- 2(8) → 1961 2(4)
- 2(93) → 1961 2(40)
- 2(94) → 1961 2(41)
- 2(97) → 1961 2(41A)
- 2(96) → 1961 2(42)
- 2(101) → 1961 2(42A)
- 2(102) → 1961 2(42B)
- 2(103) → 1961 2(42C)
- 2(106) → 1961 2(43)
- 2(107) → 1961 2(44)
- 2(108) → 1961 2(45)
- 2(109) → 1961 2(47)
- 2(111) → 1961 2(47A)
- 2(112) → 1961 2(48)
- 2(9) → 1961 2(5)
- 2(10) → 1961 2(6)
- 2(11) → 1961 2(7)
- 2(12) → 1961 2(7A)
- 2(13) → 1961 2(8)
- 2(14) → 1961 2(9A)
- 2(15) → 1961 2(9B)
- 1961 Section 36
- 1961 Section 43
- 1961 Section 43A
- 1961 Section 43B
- 1961 Section 43D
- 1961 Section 44AB
- 1961 Section 44DB
- 1961 Section 45
- 1961 Section 47
- 1961 Section 48
- 1961 Section 49
- 1961 Section 50C
- 1961 Section 54GA
- 1961 Section 55
- 1961 Section 55A
- 1961 Section 56
- 1961 Section 80C
- 1961 Section 80D
- 1961 Section 80DDB
- 1961 Section 80EEA
- 1961 Section 80LA
- 1961 Section 80P
- 1961 Section 80TTB
- 1961 Section 92F
- 1961 Section 94B
- 1961 Section 111A
- 1961 Section 112A
- 1961 Section 115A
- 1961 Section 115AB
- 1961 Section 115ACA
- 1961 Section 115C
- 1961 Section 115JB
- 1961 Section 115JF
- 1961 Section 115VP
- 1961 Section 139
- 1961 Section 139A
- 1961 Section 142A
- 1961 Section 145A
- 1961 Section 194A
- 1961 Section 194-IA
- 1961 Section 194LC
- 1961 Section 196A
- 1961 Section 201
- 1961 Section 206C
- 1961 Section 269SS
- 1961 Section 269ST
- 1961 Section 269T
- 1961 Section 271J
- 1961 Section 281B
- 2(33) → 1961 No counterpart
- 2(40)(E)(III) → 1961 No counterpart
From the Income Tax Department's correspondence.
In this Act, unless the context otherwise requires,—
(c) any income derived from any building owned and occupied by the receiver of the rent or revenue of any such land, or occupied by the cultivator or the receiver of rent-in-kind, of any such land with respect to which, or the produce of which, any process mentioned in sub-clause (b)(ii) and (iii) is carried on, where such building—
(i) is on or in the immediate vicinity of such land and that land is assessed to land revenue in India, or is subject to a local rate assessed and collected by officers of the Government as such, or where the land is not so assessed to land revenue or subject to a local rate it is not situated in any area as specified in clause (22)(iii)(A) or (B); and
but shall not include—
(6) "amalgamation", in relation to companies, means the merger of one or more companies with another company or the merger of two or more companies to form one company (the company or companies which so merge being referred to as the amalgamating company or companies and the company with which they merge or which is formed as a result of such merger being referred to as the amalgamated company) in such a manner that—
(c) the shareholders holding not less than three-fourths in value of the shares in the amalgamating company or companies (other than shares already held therein immediately before the amalgamation by, or by a nominee for, the amalgamated company or its subsidiary) become shareholders of the amalgamated company by virtue of the amalgamation,
otherwise than as a result of the acquisition of the property of one company by another company pursuant to the purchase of such property by the other company or as a result of the distribution of such property to the other company after the winding up of the first-mentioned company;
(11) "assessee" means a person by whom any tax or any other sum of money is payable under this Act, and includes—
in respect of which the same percentage of depreciation is prescribed;
(19) "books or books of account" includes ledgers, day-books, cash books, account-books and other books, whether kept—
(ii) an investment fund specified in section 224(10)(a) which has invested such securities in accordance with the provisions of the regulations made under the Securities and Exchange Board of India Act, 1992 (15 of 1992) or under the International Financial Services Centres Authority Act, 2019 (50 of 2019);
but does not include—
(B) in any area within the distance as specified in column C of the following Table, measured aerially from the local limits of any municipality or cantonment board referred to in item (A) and having population as referred to in column B of the said Table:—
TABLE
where,—
(B) "personal effects" means any movable property (including wearing apparel and furniture) held for personal use by the assessee or any family member dependent on him, but excludes—
(d) a mutual benefit finance company, that is to say, a company which carries on, as its principal business, the business of acceptance of deposits from its members and which is declared by the Central Government under section 406 of the Companies Act, 2013 (18 of 2013), to be a Nidhi or Mutual Benefit Society; or
(e) a company, wherein shares (excluding those entitled to a fixed rate of dividend, with or without a further right to participate in profits) carrying not less than 50% of the voting power, have been unconditionally, allotted to or acquired by, and were beneficially held throughout the relevant tax year by, one or more co-operative societies; or
(f) a company which is not a private company as defined in the Companies Act, 2013 (18 of 2013), and either of the following conditions is fulfilled:—
(i) shares in the company (not being shares entitled to a fixed rate of dividend, with or without a further right to participate in profits) were, as on the last day of the relevant tax year, listed in a recognised stock exchange in India as per the Securities Contracts (Regulation) Act, 1956 (42 of 1956) and any rules made thereunder;
(ii) shares in the company (not being those entitled to a fixed rate of dividend, with or without a further right to participate in profits) carrying not less than 50% of the voting power, have been unconditionally, allotted to or acquired by, and were beneficially held throughout the relevant tax year by—
so, however, that in respect of an Indian company whose business consists mainly in the construction of ships or in the manufacture or processing of goods or in mining or in the generation or distribution of electricity or any other form of power, the expression "not less than 50%" shall be read as if the expression "not less than 40%" had been substituted;
(32) 1["co-operative society" means a co-operative society registered under the Co-operative Societies Act, 1912 (2 of 1912), or the Multi-State Co-operative Societies Act, 2002 (39 of 2002), or under any other law in force in any State or Union territory for the registration of co-operative societies;]
(35) "demerger", in relation to companies, means the transfer, pursuant to a scheme of arrangement under sections 230 to 232 of the Companies Act, 2013 (18 of 2013), by a demerged company of its one or more undertakings to any resulting company in such a manner that—
(c) the property and the liabilities of the undertaking or undertakings being transferred by the demerged company are transferred at values appearing in its books of account immediately before the demerger, except in compliance to the Indian Accounting Standards specified in Annexure to the Companies (Indian Accounting Standards) Rules, 2015 made under the Companies Act, 2013 (18 of 2013);
(e) the shareholders holding not less than three-fourths in value of the shares in the demerged company (other than shares already held therein immediately before the demerger, or by a nominee for, the resulting company or, its subsidiary) become shareholders of the resulting company or companies by virtue of the demerger, otherwise than as a result of the acquisition of the property or assets of the demerged company or any undertaking thereof by the resulting company;
where,—
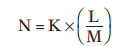
(iv) the splitting up or the reconstruction of any authority or a body constituted or established under a Central Act or State Act or Provincial Act, or a local authority or a public sector company, into separate authorities or bodies or local authorities or companies, as the case may be, shall be deemed to be a demerger if it fulfils such conditions as the Central Government may, by notification, specify;
(v) the reconstruction or splitting up of a company, which ceased to be a public sector company as a result of transfer of its shares by the Central Government, into separate companies, shall be deemed to be a demerger, if it has been made to give effect to any condition attached to the said transfer of shares and also fulfils such other conditions as the Central Government may, by notification, specify;
(39) "Director General or Director" means a person appointed to be a Director General of Income-tax or a Director of Income-tax, under section 237(1), and includes a Principal Director General or a Principal Director or an Additional Director or a Joint Director or a Deputy Director or an Assistant Director;
(b) any distribution to its shareholders by a company of debentures, debenture-stock, or deposit certificates in any form, with or without interest, and any distribution to its preference shareholders of shares by way of bonus, to the extent to which the company possesses accumulated profits, whether capitalised or not;
(e) any payment by a company, not being a company in which the public are substantially interested, of any sum (whether as representing a part of the assets of the company or otherwise),—
to the extent to which the company in either case possesses accumulated profits;
(f) 2[***]
but does not include—
(v) 3[any advance or loan between two group entities, where,—
for the purposes of items (B) and (C), the country or territory outside India shall be specified by the Central Government, by notification,]
where,—
(II) sub-clause (c), shall include all profits of the company up to the date of liquidation, but shall not, where the liquidation is consequent on the compulsory acquisition of its undertaking by the Government or a corporation owned or controlled by the Government under any law in force, include any profits of the company before three successive tax years immediately preceding the tax year in which such acquisition took place;
(I) "Finance Company" and "Finance Unit" shall have the same meaning as respectively assigned to them in regulation 2(1)(e) and (f) of the International Financial Services Centres Authority (Finance Company) Regulations, 2021 made under the International Financial Services Centres Authority Act, 2019 (50 of 2019), and is set up as a global or regional corporate treasury centre for undertaking treasury activities or treasury services as per the relevant regulations made by the International Financial Services Centres Authority established under section 4 of the said Act;
(II) 3a["group entity" shall have the same meaning as assigned to the expression "group entities" in clause (m) of sub-regulation (1) of regulation 2 of the International Financial Services Authority (Payment Services) Regulations, 2024 made under the International Financial Services Centres Authority Act, 2019 (50 of 2019);
(g) the value of any benefit or perquisite, whether convertible into money or not, obtained from a company, either by a director or by a person who has a substantial interest in the company, or by a relative of the director or such person, and any sum paid by any such company in respect of any obligation which, but for such payment, would have been payable by the director or that person;
(h) the value of any benefit or perquisite, whether convertible into money or not, obtained by any representative assessee mentioned in section 303(1)(c) or (d) or by any person on whose behalf or for whose benefit any income is receivable by the representative assessee (such person being herein referred to as the beneficiary), and any sum paid by the representative assessee in respect of any obligation which, but for such payment, would have been payable by the beneficiary;
(52) "India" means the territory of India as referred to in article 1 of the Constitution, its territorial waters, seabed and sub-soil underlying such waters, continental shelf, exclusive economic zone or any other maritime zone as referred to in the Territorial Waters, Continental Shelf, Exclusive Economic Zone and Other Maritime Zones Act, 1976 (80 of 1976), and the air space above its territory and territorial waters;
(53) "Indian company" means a company formed and registered under the Companies Act, 2013 (18 of 2013) and includes—
the registered or principal office of which is in India;
(55) "infrastructure capital company" means a company which makes investments by acquiring shares or providing long-term finance to—
(56) "infrastructure capital fund" means a fund operating under a trust deed registered under the Registration Act, 1908 (16 of 1908) established to raise moneys by the trustees for investment by acquiring shares or providing long-term finance to enterprises or undertakings referred to in clause (55);
(66) "liable to tax", in relation to a person and with reference to a country, means that there is an income-tax liability on such person under the law of that country for the time being in force and shall include a person who has subsequently been exempted from such liability under the law of that country;
(69) "manufacture", with its grammatical variations and cognate expressions, means a change in a non-living physical object or article or thing—
whether or not such an association of persons or a body of individuals or a local authority or an artificial juridical person was formed or established or incorporated with the object of deriving income, profits, or gains;
(79) "person who has a substantial interest in the company", in relation to a company means a person who is the beneficial owner of shares, not being shares entitled to a fixed rate of dividend, whether with or without a right to participate in profits, carrying not less than 20% of the voting power;
(85) "principal officer", with reference to a local authority or a company or any other public body or any association of persons or any body of individuals, means—
(87) "public sector bank" means the State Bank of India constituted under the State Bank of India Act, 1955 (23 of 1955), a corresponding new bank constituted under section 3 of the Banking Companies (Acquisition and Transfer of Undertakings) Act, 1970 (5 of 1970), or under section 3 of the Banking Companies (Acquisition and Transfer of Undertakings) Act, 1980 (40 of 1980) and a bank included in the category "other public sector banks" by the Reserve Bank of India;
(iv) deducting tax under section 393(1) [Table: Sl. No. 1(i)], [Table: Sl. No. 5(i)], [Table: Sl. No. 5(ii)], [Table: Sl. No. 5(iii)] and (Table: Sl. No. 7) or in section 393(3)(Table: Sl. No. 1), (Table: Sl. No. 2) and (Table: Sl. No. 3),
means the rate or rates of income-tax specified in this behalf in the Finance Act of the relevant year;
(b) computing the advance tax payable under Chapter XIX-C in a case falling under section 207 or 194(1) (Table: Sl. No. 1) or 194(1) (Table: Sl. No. 6) or 214 or 307 or 308 or 311 the rate or rates specified in the said respective section, or the rate or rates of income-tax specified in this behalf in the Finance Act of the relevant tax year, whichever is applicable;
(c) deducting tax under section 393(2) (Table: Sl. No. 6), (Table: Sl. No. 7), (Table: Sl. No. 8), (Table: Sl. No. 9) and (Table: Sl. No. 17), the rate or rates of income-tax specified in this behalf in the Finance Act of the relevant tax year or the rate or rates of income-tax specified in an agreement entered into by the Central Government under section 159(1), or an agreement notified by the Central Government under section 159(2), whichever is applicable;
(91) "recognised provident fund" means a provident fund which has been and continues to be recognised by the approving authority as per Part A of the Schedule XI, and includes a provident fund established under a scheme framed under the Employees' Provident Funds and Miscellaneous Provisions Act, 1952 (19 of 1952);
(97) "resulting company" means one or more companies (including a wholly owned subsidiary thereof) to which the undertaking of the demerged company is transferred in a demerger and, the resulting company in consideration of such transfer of undertaking, issues shares to the shareholders of the demerged company and includes any authority or body or local authority or public sector company or a company established, constituted or formed as a result of demerger;
the provisions of sub-clause (a) shall have effect, as if for the words "twenty-four months", the words "twelve months" had been substituted; and
(IV) the person was a member of a recognised stock exchange in India immediately before its demutualisation or corporatisation, for a capital asset, being trading or clearing rights of that recognised stock exchange, acquired by a person pursuant to such demutualisation or corporatisation of that recognised stock exchange;
(II) the date of allotment of a share or any other security (herein referred to as the financial asset), for a capital asset being such financial asset subscribed to by the assessee on the basis of his right to subscribe to such financial asset or subscribed to by the person in whose favour the assessee has renounced his right to subscribe to such financial asset;
(V) the date of allotment or transfer of any specified security or sweat equity shares allotted or transferred, directly or indirectly, by the employer free of cost or at concessional rate to his employees (including former employee or employees), for a capital asset being such specified security or sweat equity shares;
where,—
(105) "stamp duty value" means the value adopted or assessed or assessable by any authority of the Central Government or State Government for the payment of stamp duty in respect of an immovable property, where the expression "assessable" shall mean the value which any authority of that Government would have adopted or assessed as if it were referred to such authority for the purposes of payment of stamp duty, irrespective of anything to the contrary contained in any other law in force;
(f) any transaction (whether by way of becoming a member of, or acquiring shares in, a co-operative society, company or other association of persons or by way of any agreement or any arrangement or in any other manner) which has the effect of transferring, or enabling the enjoyment of, any immovable property; or
(h) disposing of, or parting with, an asset or any interest therein, or creating any interest in any asset in any manner, directly or indirectly, absolutely or conditionally, voluntarily or involuntarily, by way of an agreement (whether entered into in India or outside India) or otherwise, irrespective of whether such transfer of rights has been characterised as being effected or dependent upon or flowing from the transfer of a share or shares of a company registered or incorporated outside India,
where, the expression "immovable property" means—
(i) any land or any building or part of a building, and includes, where any land or any building or part of a building is to be transferred together with any machinery, plant, furniture, fittings or other things, such machinery, plant, furniture, fittings or other things also, such that the land, building, part of a building, machinery, plant, furniture, fittings and other things include any rights therein;
(ii) any rights in or with respect to any land or any building or a part of a building (whether or not including any machinery, plant, furniture, fittings or other things therein), which has been constructed or which is to be constructed, accruing or arising from any transaction (whether by way of becoming a member of, or acquiring shares in, a co-operative society, company or other association of persons or by way of any agreement or any arrangement of whatever nature), not being a transaction by way of sale, exchange or lease of such land, building or part of a building;
(a) any information or code or number or token (not being Indian currency or foreign currency), generated through cryptographic means or otherwise, called by any name, providing a digital representation of value exchanged with or without consideration, with the promise or representation of having inherent value, or functions as a store of value or a unit of account including its use in any financial transaction or investment, but not limited to investment scheme; and can be transferred, stored or traded electronically;
where,—
where, the expression "infrastructure debt fund" means the infrastructure debt fund notified by the Central Government under Schedule VII (Table: Sl. No. 46).
Footnotes
- 1.Sub. by the Act No. 4 of 2026, w.e.f. 1-4-2026. Prior to its substitution, clause (32) read as under : '(32) "co-operative society" means a co-operative society registered under the Co-operative Societies Act, 1912 (2 of 1912), or under any other law in force in any State or Union territory for the registration of co-operative societies;'↩
- 2.Omtt. by the Act No. 4 of 2026, w.e.f. 1-4-2026. Prior to its omission, sub-clause (f) read as under : '(f) any payment by a company on purchase of its own shares from a shareholder as per section 68 of the Companies Act, 2013 (18 of 2013),'↩
- 3.Sub. by the Act No. 4 of 2026, w.e.f. 1-4-2026. Prior to its substitution, sub-clause (v) read as under : '(v) any advance or loan between two group entities, where,— (A) one of the group entity is a "Finance Company" or a "Finance Unit"; and (B) the parent entity or principal entity of such group is listed on stock exchange in a country or territory outside India other than the country or territory outside India as specified by the Board in this behalf,'↩
- 3a.Items (II) and (III) sub. for item (II) by the Act No. 4 of 2026, w.e.f. 1-4-2026. Prior to its substitution, item (II) read as under : '(II) "group entity", "parent entity" and "principal entity" shall be such entities which satisfy such conditions as may be prescribed in this behalf;'↩