2025Section 99
99. Income of individual to include income of spouse, minor child, etc.
(1) The total income of any individual, for a tax year, shall include the income arising directly or indirectly,—
(i) by way of salary, commission, fees or any other form of remuneration, whether in cash or kind, from a concern in which such individual has a substantial interest but shall not include income solely attributable to the application of technical or professional knowledge, experience and technical or professional qualification of the spouse;
(d) to any person or association of persons from assets transferred directly or indirectly, otherwise than for adequate consideration to the person or association of persons by such individual, to the extent to which the income from such assets is for the immediate or deferred benefit of his or her spouse or his son's wife, as the case may be, other than the assets transferred before 1st June 1973, to the extent to which the income from such assets is for the immediate or deferred benefit of his son's wife.
(2) If the asset transferred under 11[sub-section (1)(a)(ii) or (b)] is invested by the spouse or son's wife, in any business or in the nature of capital contributed as a partner in a firm, or, as the case may be, for being admitted to the benefits of partnership in a firm, then, the income to be included in the hands of the individual for the tax year shall be as follows:—
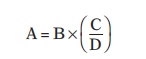
where ,—
(3) Where a property owned by an individual is converted into property belonging to the Hindu undivided family of which he is a member, through—
without adequate consideration, then, irrespective of any other provision of this Act or any other law in force for computing the total income of such individual,—
(ii) where the property so converted has been the subject-matter of partition (whether partial or total) amongst the member of the family, the income derived from such property as is received by the spouse of the individual on partition, shall be deemed to arise to the spouse from assets transferred indirectly to the spouse and the provisions of sub-section (1)(a) shall apply,
and the income referred to in clauses (i) and (ii) shall, on being included in the total income of the individual, be excluded from the total income of the family or the spouse.
(A) in case where the concern is a company, if its shares (not being shares entitled to a fixed rate of dividend whether with or without a further right to participate in profits) carrying not less than 20% of the voting power are, at any time during the tax year, owned beneficially by the individual or jointly with one or more of his relatives;
and such income, once included in the total income of either of the parent, for a tax year, shall not be included in the income of the other parent for any succeeding tax year, unless the Assessing Officer is so satisfied, after giving the other parent an opportunity of being heard;
Footnotes
- 11.Sub. for "sub-section (1)(a)(i) or (b)" by Act No. 4 of 2026, w.e.f. 1-4-2026.↩